 by
Corporate Real Estate Valuation: Methods, Strategies, and Practical Applications
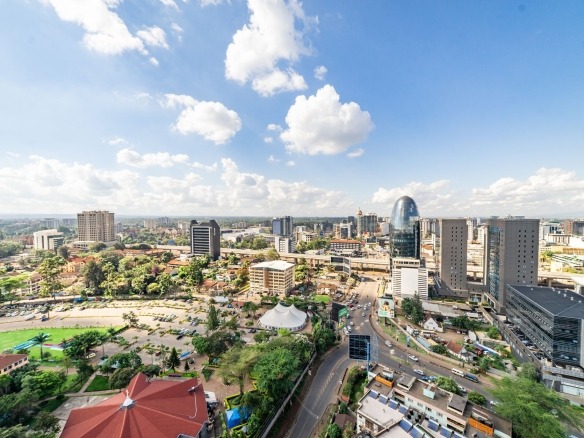
Corporate real estate is one of the most significant assets on a company’s balance sheet. Whether it’s an office block in Nairobi’s Upper Hill, a logistics warehouse in Athi River, or a retail centre in Westlands, these properties often represent millions—if not billions—of shillings in value. That makes corporate real estate valuation a cornerstone of sound financial management, investment planning, and regulatory compliance.
This guide explores the core valuation methodologies, the frameworks that govern them, and how businesses can use rigorous valuations to make smarter strategic decisions. Whether you’re a CFO preparing IFRS-compliant reports or a property manager evaluating portfolio performance, understanding these principles is essential.
—
Why Corporate Real Estate Valuation Matters
Corporate real estate valuation goes far beyond calculating what a property might sell for. It supports several critical business functions:
– Financial reporting: Aligns property values with IFRS or GAAP standards for audit-ready financial statements.
– Investment strategy: Guides acquisition, disposal, and development decisions with reliable data.
– Risk management: Identifies exposure to market swings, vacancy risks, and insurance shortfalls.
– Regulatory compliance: Ensures adherence to statutory and corporate governance requirements.
Unlike a standard residential appraisal, corporate valuation involves complex lease structures, interdependent portfolios, and strategic asset objectives. A professional valuation helps leadership align property holdings with broader business goals—ensuring capital is deployed effectively and risks are well understood.
—
Valuation Standards and Governance
Professional standards ensure consistency, transparency, and defensibility. The most recognised frameworks include:
– International Valuation Standards (IVS): Globally accepted definitions, methodologies, and reporting protocols.
– RICS Red Book: Professional guidance covering ethics, documentation, and compliance.
– IFRS and GAAP: Fair value measurement requirements, particularly IAS 16 and IAS 40, which are critical for corporate reporting.
Integrating these standards produces valuations that stand up to audit scrutiny, lending due diligence, and transaction negotiations.
—
Choosing the Right Basis of Value
The basis of value determines how a property is assessed. Different purposes call for different approaches:
| Basis of Value | Definition | Common Use |
|—————-|————-|————|
| Market Value | Price obtainable in a competitive market between willing buyer and seller | Transactions, financial reporting |
| Fair Value | IFRS-defined price in an orderly sale, reflecting market participant assumptions | IFRS compliance, financial statements |
| Investment Value | Value to a specific investor, considering financing and strategy | Internal investment decisions, portfolio planning |
| Special/Forced Sale Value | Value under constrained or distressed conditions | Insolvency, liquidation, accelerated sales |
Selecting the correct basis is critical. It shapes the outcome, how results are interpreted, and whether the valuation meets regulatory and accounting requirements.
—
Core Valuation Methodologies
There are four primary methods used in corporate real estate valuation. Each has its strengths, applications, and limitations.
1. Income Capitalisation Approach
This method converts expected property income into present value using capitalisation (cap) rates.
Best for: Income-producing assets like office buildings, retail centres, and industrial properties.
Key adjustments: Vacancy allowances, rent-free periods, lease escalations, and operating expenses.
Limitation: Heavily reliant on market-derived cap rates, which can shift with interest rates and investor sentiment.
2. Discounted Cash Flow (DCF) Analysis
DCF projects future cash flows and discounts them to present value, incorporating risk adjustments.
Best for: Development projects, complex portfolios, and properties with variable income streams.
Strengths: Captures the timing of cash flows, capital expenditure, and growth assumptions.
Challenge: Requires accurate long-term projections and robust sensitivity analysis.
3. Cost Approach
Value is estimated based on reproduction or replacement cost, less depreciation.
Best for: Specialised or owner-occupied properties with few market comparables.
Limitation: May not reflect current market conditions. Often used as a corroborative method alongside others.
4. Sales Comparison Approach
This benchmarks against recent transactions of similar properties, adjusting for differences.
Adjustment factors: Size, location, condition, age, lease structure, occupancy, and market liquidity.
Best for: Land, office properties, and retail assets in markets with sufficient comparable sales.
Limitation: Data availability is essential. Less effective in opaque or thin markets.
—
Valuation Across Property Types
Different real estate assets present unique valuation considerations.
Office and Commercial Properties
– Tenant quality and creditworthiness
– Lease duration and escalation clauses
– Building grade and specifications
– Location, accessibility, and amenities
Industrial and Logistics Facilities
– Functional utility: ceiling height, floor load, truck access
– Proximity to transport corridors and ports
– Lease terms and tenant stability
– Expansion or redevelopment potential
Retail and Mixed-Use Developments
– Tenant mix and turnover-linked leases
– Footfall and consumer spending trends
– Anchor tenant influence
– Integrated assessment of residential, commercial, and leisure components
Specialised Institutional Properties
– Operational and functional analysis
– Cost-based reconstruction estimates
– Compliance with regulatory or statutory constraints
—
Practical Example: A Portfolio Valuation in Action
Consider a multinational corporation with a 50,000 m² mixed-use portfolio—offices, retail, and an industrial facility.
Step 1: Segregate property types for tailored analysis.
Step 2: Apply income capitalisation to retail and industrial units, adjusting for vacancy and expenses.
Step 3: Use DCF for the office building, which has variable lease income.
Step 4: Cross-validate specialised assets with the cost approach.
Step 5: Consolidate results into a portfolio valuation for IFRS-aligned reporting.
Outcome: A defensible, audit-ready valuation supported by sensitivity analysis, factoring in market changes, lease renewal risks, and ESG compliance costs.
—
Emerging Challenges in Corporate Valuation
Valuation professionals face growing complexity:
– Market volatility: Interest rates, economic cycles, and geopolitical events all affect property values.
– Data gaps: In emerging markets, limited transactional evidence requires professional judgment.
– Complex structures: Multi-tenant arrangements, easements, and shared ownership complicate analysis.
– ESG and sustainability: Energy performance, carbon compliance, and green certifications increasingly influence value.
—
Technology and Innovation
Advances in technology are reshaping the valuation field:
– GIS mapping for location-specific risk assessment
– PropTech platforms for automated data aggregation and benchmarking
– AI-enabled DCF models for scenario analysis and forecasting
– Digital reporting tools for interactive dashboards and audit-ready documentation
These tools complement professional judgment, enabling faster, more transparent, and more responsive valuations.
—
Strategic Implications for Business Leaders
A rigorous corporate real estate valuation framework supports:
– Investment decisions—acquisition, disposal, and development strategy
– Portfolio optimisation—capital allocation and asset rationalisation
– Risk management—insurance adequacy, financing, and compliance
– Governance—board reporting, internal controls, and audit readiness
Organisations that invest in high-quality valuation services gain a clearer view of their property holdings, enabling better decisions, stronger accountability, and long-term value creation.
—
Conclusion
Corporate real estate valuation is a vital practice for any organisation holding significant property assets. By applying proven methodologies—income capitalisation, DCF, cost, and sales comparison—businesses can achieve credible, transparent, and defensible assessments.
Compliance with IVS, RICS, and IFRS standards ensures consistency and audit readiness. Meanwhile, emerging trends like ESG integration and technological innovation are reshaping how valuations are performed and interpreted.
In a market where real estate decisions carry significant financial weight, organisations that embrace rigorous valuation practices are better positioned to mitigate risk, optimise portfolios, and make strategic choices that drive sustainable growth.
—
For further reading, consult the RICS Valuation – Global Standards (Red Book), the International Valuation Standards (IVSC), and relevant IFRS guidance on fair value measurement.
Join The Discussion